You just got a repair quote that made your stomach drop, or maybe the water heater is making a noise you have never heard before. Either way, you are here because something in your house needs money you were not planning to spend.
That feeling gets a lot less scary once you have a real number to work with. Budgeting for home repairs comes down to setting aside a specific percentage of your home's value each year, then splitting that into routine upkeep, planned repairs, and a cushion for surprises. Once you have that structure, a broken dishwasher stops feeling like a crisis and starts feeling like a line item.
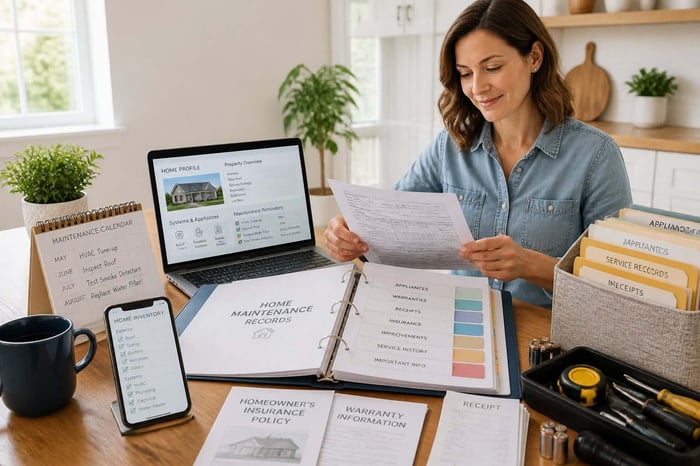
This is also where keeping good records pays off. A tool like Manse lets you attach warranty dates, manuals, and service history to each appliance, so when something breaks, you already know what it will cost to fix and whether it is still covered.
Keep reading to learn how to set your number, split it into the right buckets, plan for big-ticket items, and turn it into a monthly habit you can actually stick with.
Set a Repair Budget That Fits Your Home
Start your repair budget with a percentage of your home's value, not a guess pulled from thin air. Two simple methods get you close, and then you adjust based on your specific house.
Start With the 1% to 4% Rule
The most common starting point is setting aside 1% to 4% of your home's value each year for repairs and maintenance. For a $300,000 home, that's $3,000 to $12,000 a year, depending on age and condition.
This range exists because homes vary so much. A 5-year-old house in a mild climate sits at the low end. A 40-year-old house with an original furnace sits at the high end.
Start at 2% if you are not sure where you fall. That gives you a workable middle number while you gather more information about your specific systems and their age.
Use the Square Footage Method as a Quick Check
A square footage estimate works as a fast gut check against the percentage method. Multiply your home's square footage by a set dollar amount, often between $1 and $2 per square foot annually, to get a comparable figure.
A 2,000-square-foot home would land between $2,000 and $4,000 a year under this method. If that number is far off from your 1% to 4% calculation, it is worth digging into why.
Run both numbers side by side once a year. If they roughly match, you can trust your budget. If they diverge sharply, your home's age or condition is likely skewing one method.
Adjust Your Number for Age, Condition, and Climate
Your final number needs adjusting for three things: how old your home is, how well it has been maintained, and where you live. An older home from the 1970s or earlier tends to sit at the high end of the 1% to 4% range, between deferred maintenance and modernization needs that newer homes simply don't carry.
Climate matters just as much as age. Homes in areas with harsh winters or high humidity wear out roofs, gutters, and HVAC systems faster than homes in mild, dry climates.
Use this quick checklist to decide where you land on the 1% to 4% scale:
- Home is under 10 years old and well maintained: lean toward 1% to 2%
- Home is 10 to 30 years old with average upkeep: lean toward 2% to 3%
- Home is over 30 years old or has deferred maintenance: lean toward 3% to 4%
- You live in a harsh climate (heavy snow, high humidity, coastal salt air): add half a percentage point
Once you have a number you trust, the next step is deciding exactly where that money goes and what it is not meant to cover.
Separate Routine Upkeep, Repairs, and Renovations
These three cost categories need separate homes in your budget, because mixing them is how homeowners run out of money mid-project. Routine upkeep, repairs, and renovations behave differently and deserve different funding sources.
What Belongs in a Home Repair Fund
Your repair fund should cover unplanned, necessary fixes: a leaking dishwasher hose, a broken garage door spring, a water heater that suddenly stops heating. You can't predict these costs exactly, but you know they will happen eventually.
Think of this fund as your safety net for anything that breaks without warning. It is not for upgrades or things that still work fine but look dated.
A good test is to ask whether the item still functions. If your oven stopped heating, that is a repair. If your oven works but you want a nicer one, that is a renovation decision, not a repair emergency.
Which Costs Should Come From Your Monthly Budget
Routine upkeep should come out of your regular monthly budget, not your repair fund. This includes HVAC filter changes, gutter cleaning, lawn care, and seasonal furnace checks.
These costs are predictable and recurring, so they belong alongside your other monthly bills like utilities or groceries. Treating them as monthly expenses instead of surprise costs keeps your repair fund reserved for the things you truly cannot plan for.
For example, changing your HVAC filter every one to three months costs very little compared to the repair bill from a system that overheats because airflow was blocked for a year. That small monthly cost is prevention, not repair.
When a Project Needs a Separate Renovation Budget
Renovations need their own dedicated budget separate from repairs, because they are chosen upgrades, not necessary fixes. A kitchen remodel or a bathroom overhaul falls here, even if it starts with a repair.
Two related but distinct guidelines are worth knowing here. The 30% rule suggests keeping your total renovation spending at or under 30% of your home's current value, so you don't over-invest relative to what the home is worth. Separately, most experts also recommend building in a 10% to 20% cushion on top of your project estimate to absorb what contractors find once walls come down.
Keeping renovation money separate protects your repair fund from getting drained by an optional project. It also keeps mid-project decisions from being driven by fear of running out of emergency cash.
With your categories separated, the next question is which repairs are likely to cost the most and deserve the closest attention.
Plan for the Repairs That Cost the Most
The biggest repair costs almost always come from major systems: roof, HVAC, water heater, and foundation. Knowing which systems are aging out lets you plan for them instead of reacting.
Track Major Systems Before They Fail
Every major system in your home has a rough lifespan, and knowing where each one stands tells you what is coming. A water heater typically lasts 8 to 12 years, while a roof can last 15 to 25 years depending on materials.
Walk through your home and note the installation date for each major system if you know it. If you do not know it, check the appliance label or manual for a manufacture date, or look for a service sticker from a past technician visit. If the label is hard to read, a guide to decoding appliance model numbers can help.
This is where a home profile in Manse becomes useful. Instead of guessing when your HVAC system was installed, you log it once with the model number and installation date, and the record stays with your home going forward.
Build a Home Repair Costs List From Your Own Records
Your own repair history is the most accurate cost predictor you have, better than any generic estimate. Pull together receipts, invoices, and service records from the last few years and note what you actually paid.
If you replaced a garbage disposal for $220 two years ago, that is a more useful number for your budget than a national average. Do this for every repair you can find records for, going back as far as your paperwork allows.
Once you have five or six real data points, patterns start to show. You might notice plumbing repairs cluster in one price range while appliance repairs cluster in another, which helps you weight your fund correctly.
Prioritize Safety, Water Damage, and Active Failures
Repairs involving safety risks or active water damage should always jump to the front of the line. A slow leak under a sink can rot a subfloor within months if ignored, turning a $150 fix into a $3,000 one.
Use this order when multiple repairs compete for the same dollars:
- Active water leaks or flooding risk (can cause structural damage fast)
- Gas, electrical, or carbon monoxide hazards (safety first, always)
- Systems that are completely non-functional (no heat, no hot water, no working stove)
- Cosmetic or comfort issues (can wait without causing further damage)
Once you know which repairs matter most and roughly what they cost, the next step is turning that yearly number into something you actually save each month.
Turn Your Annual Goal Into a Monthly Savings Plan
Your annual repair budget only works if you break it into a monthly savings habit you can sustain. A $4,000 annual goal is much easier to hit as $333 a month than as one lump sum you scramble for in December.
Keep Repair Savings Separate From Everyday Spending
Repair money needs its own account, separate from your checking account and everyday spending. Mixing it with grocery money or your emergency fund makes it too easy to spend without noticing.
A dedicated savings account, even a basic one, creates a clear line between "money I can spend today" and "money set aside for the furnace." This separation matters more than which bank or account type you choose.
Some homeowners aim to set aside the equivalent of two monthly mortgage payments each year for repairs and maintenance, a benchmark noted by financial expert Clark Howard. That gives you a second number to sanity check against your percentage-based calculation.
Set Automatic Transfers You Can Maintain
Automatic transfers remove the decision-making from saving, which is why they work better than manual transfers you have to remember. Set the transfer for the same day your paycheck lands, so the money moves before you can spend it elsewhere.
Start with an amount you can maintain for a full year, even if it is smaller than your ideal number. A $150 monthly transfer you actually keep up beats a $400 transfer you abandon after two months.
Review the amount every six months and increase it gradually as your budget allows. Small, consistent increases build the fund faster than waiting for a "better time" to start saving more.
Use a Sinking Fund for Known Replacements
A sinking fund earmarks money for one specific, known future expense, separate from your general repair fund. If you know your water heater is 9 years old and averages a 10- to 12-year lifespan, you can start saving specifically for its replacement now.
This approach spreads a high, predictable cost across many months instead of hitting your budget all at once, similar to how a sinking fund for irregular expenses works for something like car repairs or insurance premiums.
For example, if you expect a $1,800 water heater replacement in 18 months, saving $100 a month gets you there without touching your general repair fund. Log the target date and amount in your notes so the goal does not quietly fade.
With your savings plan running, the next thing to protect is keeping it accurate as your home ages and changes.
Keep Your Budget Current as Your Home Changes
Update your repair budget whenever something changes in your home, not just once a year on autopilot. A budget built for a 5-year-old roof does not fit once that roof turns 20.
Record Repairs, Receipts, Warranties, and Service Dates
Log every repair, receipt, and warranty document the moment it happens, while the details are still fresh. Waiting until later means digging through email or paper piles trying to remember what you paid and when.
Picture this: your dishwasher stops draining, and you remember it was serviced about two years ago, but you cannot recall if it is still under warranty. If you logged that date and the warranty paperwork in an app when the repair happened, you would have the answer in seconds instead of searching three inboxes. This guide on finding and storing appliance manuals is a good place to start if your paperwork is still scattered.
Keeping this history also builds the personal cost list from earlier in this guide. Every logged repair becomes a real data point that sharpens your budget for next year.
Review Your Fund After a Major Repair or Move
Your repair fund needs a full review after any major repair, a move, or a big renovation, since your home's risk profile just changed. Replacing a roof resets that system's clock, which lowers your risk in that category for the next 15 to 25 years.
Moving into a new home means starting from scratch on system ages, unless the previous owner left detailed records. Ask for maintenance history at closing when possible, and note what is missing so you know where your budget needs to lean more conservative.
A renovation can also shift your ongoing costs. A new kitchen with updated appliances lowers near-term appliance repair risk but may raise your homeowner's insurance value, so double-check it.
Use Maintenance to Reduce Avoidable Repair Bills
Routine maintenance is the cheapest way to shrink your repair budget over time, because most major repairs start as small, ignorable problems. A clogged dryer vent left uncleaned is a fire risk and a common cause of avoidable repair calls.
Simple, consistent habits prevent expensive failures, and folding them into an annual home maintenance checklist keeps them from getting missed:
- Change HVAC filters every one to three months to protect the system and lower energy bills
- Clean refrigerator condenser coils twice a year to prevent overwork and early failure
- Flush the water heater annually to extend its lifespan past the average range
- Clear gutters twice a year to protect the roof and foundation from water damage
None of this eliminates repairs entirely, but it shrinks the frequency of expensive surprises. That shift, from reacting to planning, is really the whole point of building a repair budget in the first place.
Frequently Asked Questions
How much should I budget for house repairs each month?
Most homeowners should budget 1% to 4% of their home's value per year, then divide that by 12 for a monthly figure. For a $300,000 home, that works out to roughly $250 to $1,000 a month, depending on your home's age and condition.
Is the 1% rule enough for an older home?
The 1% rule usually falls short for homes over 30 years old, since aging systems and deferred maintenance push costs higher. Homes from the 1970s or earlier often need closer to 3% to 4% of home value annually, or more if major systems have not been updated.
Should home repairs come from an emergency fund or a separate savings account?
Home repairs should come from a dedicated repair fund, not your general emergency fund, since both serve different purposes. Your emergency fund covers job loss or medical costs, while a repair fund covers predictable home wear and planned replacements.
What are the most expensive things to repair in a house?
Roofs, HVAC systems, foundations, and water heaters tend to carry the highest repair and replacement costs in a home. These major systems also have the widest cost ranges, so tracking their age and condition helps you plan ahead instead of reacting.
What is the 30% rule for home renovation?
The 30% rule suggests keeping total renovation spending at or under 30% of your home's current value, so you don't over-invest relative to what the home is worth. Most experts also recommend adding a separate 10% to 20% cushion on top of your project estimate to cover unexpected costs.
How can I estimate upcoming repairs when I just bought a house?
Start by checking the age of major systems using appliance labels, manuals, or service stickers left behind by the previous owner. If records are missing, assume mid-range lifespans for each system and lean toward the higher end of the 1% to 4% rule until you gather more history.
A Repair Fund You Can Rely On
A reliable repair fund comes from three habits working together: a realistic annual number, separate savings, and current records. Skip any one of these and the other two start to wobble.
Homeowners who feel calm about repairs aren't the ones with the biggest bank balances. They know their numbers, know their home's history, and aren't searching for a warranty card at midnight.
Manse understands your home's appliances, systems, warranties, and policies, so you always know exactly what to do. See how it works.